Overseas-founder assessment
Identify residency, nationality and activity constraints before application.
Within one working day, receive the realistic provider shortlist, UK business rationale and evidence checklist for your company.
Oxygen Empire is a Dubai-based advisory company supporting businesses and private clients across the UAE, the Middle East and international jurisdictions. We coordinate corporate, banking, relocation and compliance work around one objective—so the client does not have to manage unrelated providers and conflicting advice.
Every case starts with a confidential assessment. We explain what is realistic, what evidence is required and which decisions remain with the registry, bank, endorsing body or immigration authority.
The jurisdiction only works when its advantages match the owner's nationality, activity, transaction geography and long-term plan.
Identify residency, nationality and activity constraints before application.
Show customers, suppliers, team, operations or market plans that support the account need.
Choose around eligibility, currencies, payment tools and future requirements.
A structured onboarding project—from eligibility diagnosis to the bank's final decision.
We review the United Kingdom company, owners, residencies, sector, counterparties, currencies and expected transaction pattern.
We build a consistent file covering KYC, source of wealth/funds, contracts, business plan, website and financial forecast.
Screen high-street, specialist and regulated fintech routes against the owners and operating model.
We coordinate forms, supporting documents, director preparation and responses to compliance questions.
We track requests, close evidence gaps and reassess the route if the institution's risk appetite does not fit. Approval is never guaranteed.
Senior experts who combine legal, corporate, tax and business-development experience for cross-border projects in the UAE, MENA and international jurisdictions.
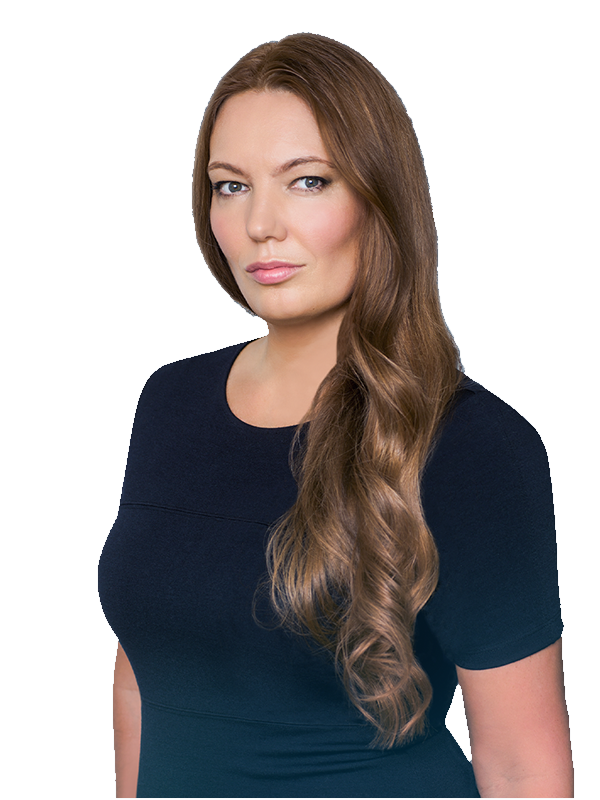
Founder and CEO of Oxygen Empire, part of the O2 Consulting group.
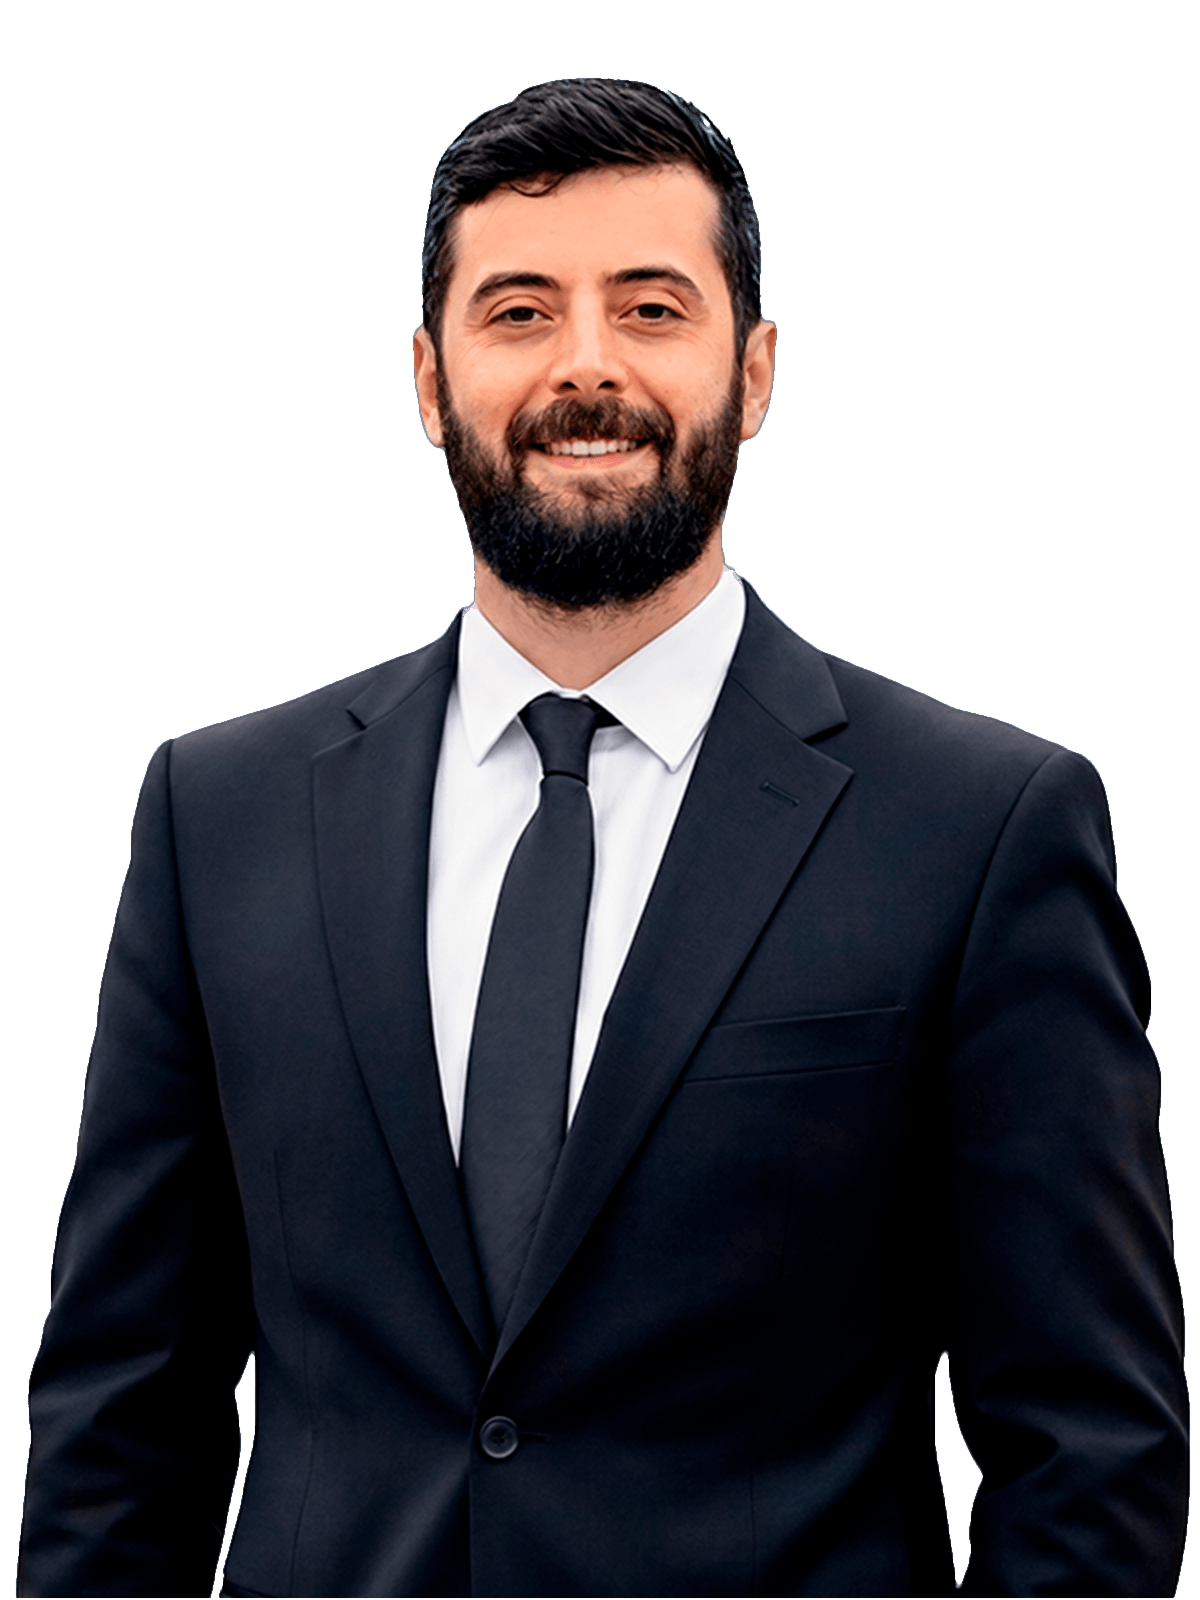
Business development and strategic consulting expert with 15+ years of experience supporting entrepreneurs and companies.
These examples show the kinds of requests our team can evaluate and structure. The exact route always depends on the client's facts, evidence and the independent decision of the relevant institution or authority.
Situation: A newly incorporated business needs an account before it has a long transaction history.
Our approach: Build the file around ownership, contracts, forecast flows and uk provider matching rather than relying on registration documents alone.
Situation: The applicant received a rejection or no clear explanation and needs to understand the likely gaps.
Our approach: Audit the previous submission, identify inconsistencies and reassess institution fit before a new application is made.
Situation: The company collects and pays in multiple currencies across several customer and supplier countries.
Our approach: Map expected flows, counterparties and settlement logic, then match the profile to institutions able to support that pattern.
Situation: A consultancy has a low volume of higher-value payments and must evidence the commercial basis of each flow.
Our approach: Prepare contracts, delivery evidence, client geography and source-of-funds explanations as one consistent compliance narrative.
Situation: The operator needs an account aligned with marketplaces, acquiring, refunds and supplier payments.
Our approach: Separate banking and payment-provider requirements, document the sales chain and prepare realistic transaction forecasts.
Situation: The bank must understand goods, shipment routes, suppliers, buyers and payment terms before onboarding.
Our approach: Create a transaction map supported by contracts and logistics evidence, and screen country and counterparty risk upfront.
Situation: A holding vehicle has fewer operating transactions but needs a clear economic purpose and source-of-wealth file.
Our approach: Explain the group structure, ownership history, expected distributions and investment activity with supporting evidence.
Situation: The beneficial owners need coordinated corporate and personal evidence for an investment-led account.
Our approach: Build one KYC pack covering source of wealth, decision makers, asset history and the role of each entity.
Situation: The company has multiple decision makers and needs a clear explanation of control and payment authority.
Our approach: Document ownership, voting rights, signing rules and responsibilities before compliance questions arise.
Situation: The client needs reliable payment operations but may not fit one traditional bank's risk appetite.
Our approach: Compare the operational need with institution capabilities and prepare a compliant primary and fallback route without promising approval.
We will send the starting list for your United Kingdom case and flag profile-specific additions.
The fastest projects begin with a complete, consistent evidence set and a clear division of responsibility.
For founders who need a realistic account route and a coherent UK story.
For businesses collecting from UK clients and paying local suppliers or staff.
For transparent online models with documented platforms, clients and payment flows.
For subsidiaries and branches with established ownership and financial history.
Tell us the objective, ownership, timing and current stage. We will come back with the realistic route, key evidence and a proposed scope.